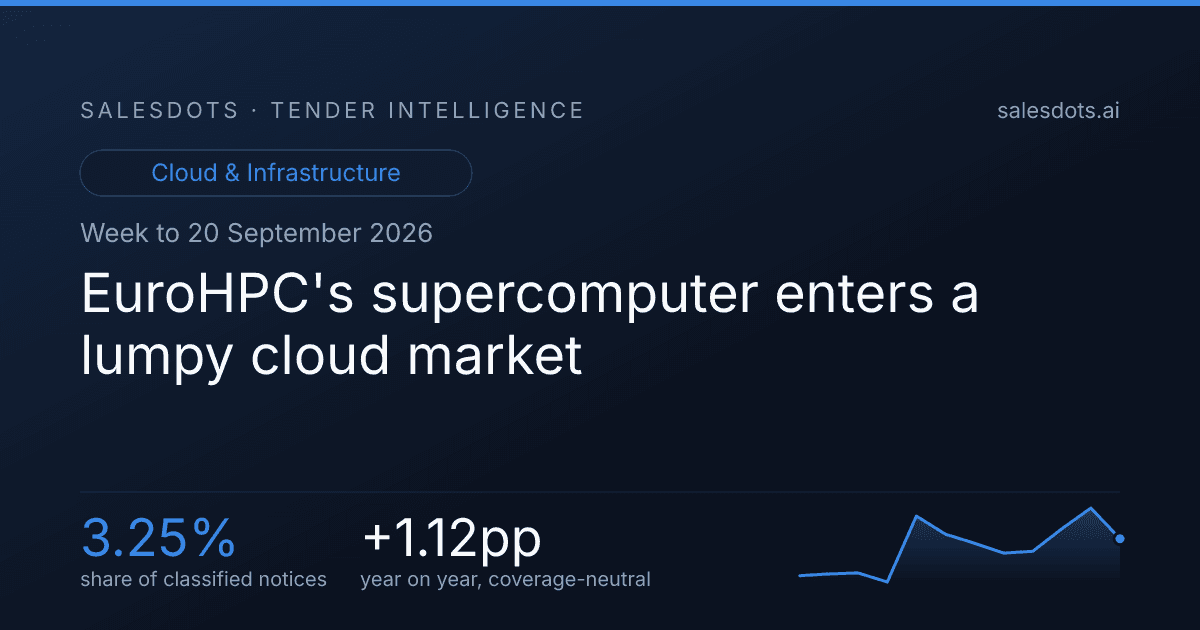
EuroHPC's supercomputer enters a lumpy cloud market
EuroHPC's supercomputer tender sits beside a 3.25% procurement share, a 1.7-bid Spanish field, and sharp falls for Dell and Oracle.
The European High-Performance Computing Joint Undertaking is seeking acquisition, delivery, installation and hardware and software maintenance for its INNOVATE industrial-grade supercomputer in Luxembourg, with a published value of €11,615,385. EuroHPC pools European and Member State resources for high-performance computing procurement, making this a named route into a buyer whose remit extends beyond a conventional server refresh.
For bid teams, the immediate mix is not solely hardware. System implementation appears in 43 notices and is 43% above its 12-week average; custom development has 21 notices and is 66% above; licences SaaS has 17 notices and is 127% above. The shift towards build and integration work sits alongside a fall of 12% for support and maintenance, which has 6 notices.
Where this market is going
Cloud & Infrastructure accounts for 3.25% of the classified corpus in the current window, a coverage-neutral rise of 1.12 percentage points from 2.13%. Do not read the raw move to 208 notices from 74 as market growth: collection coverage has changed. The share movement, rather than the notice count, is the signal bidders can use.
The monthly path is lumpy rather than steady. Share edged from 2.22% in September 2025 to 2.24% in October and 2.25% in November, before falling to 2.15% in December. It then jumped to 2.88% in January 2026, eased through 2.68% in February, 2.58% in March and 2.47% in April, then recovered to 2.49% in May, 2.74% in June and 2.97% in July before dropping to 2.63% in August. The current 3.25% reading is therefore an upswing after a volatile sequence, not evidence of a smooth expansion.
Cloud & Infrastructure: share of all classified public IT tenders
Share, not volume. Monthly, last 12 complete months.
Where the tenders were published
Notices by buyer country, 14 days to 2026-09-20.
How hard the competition is
The overall average is 2.7 bids across 31 measured cases, but country contrast matters more. Germany is the crowded field at 3.6 bids, while Poland is at 2.3, Czechia at 2.5 and Spain at 1.7. A German pursuit needs differentiation and technical quality, not price alone. In Spain, the lower bid count means qualification, local delivery capacity and a credible execution team are likely to constrain the field more than price alone.
Price is recorded in 92 cases and quality in 18, with 94 unstated, so teams should not mistake a price-led scorecard for a licence to submit an undifferentiated offer. SMEs are winning 78% of the measured work, while 35% is single-bid. That combination favours properly qualified specialists in thin markets, but it also makes early bidder qualification and partner coverage essential where incumbents can leave a buyer with only one credible response.
How these contracts are awarded
Stated award criterion, for the tenders that declared one.
What is driving it
Poland's Ustawa o krajowym systemie cyberbezpieczeństwa is the active citation signal, appearing in 5 tenders in this window. Its broader 30-day series records 282 tenders against 218 in the previous 30 days. NIS2 is flat at 3 tenders in both periods; CBAM is at 1 against 0; DORA is at 1 against 0; and DPM 2.0 is at 1 against 0. These are not interchangeable demand pools, but they identify where security, reporting and data-control requirements are beginning to enter infrastructure buying language.
The more defined cloud build is Article 16 of AMLD6. It requires centralised automated mechanisms for identifying account holders and controllers, with access for FIUs, AMLA and supervisory authorities, and interconnection through BARIS. The calendar puts application on 10 July 2027 and BARIS on 10 July 2029. The EU AML Package also applies on 10 July 2027, with AMLA direct supervision from 1 January 2028; the Solvency II Review has a transposition deadline of 29 January 2027 and applies from 30 January 2027. This is both product procurement and compliance work: buyers need register or data-retrieval capability, interconnection and controlled data flows, alongside the implementation work needed to satisfy the new rules.
Regulations named in live tenders
Tenders citing each framework, last 30 days.
The calendar ahead
| Date | Framework | Milestone | Where |
|---|---|---|---|
| 2027-01-29 | Solvency II Review (Directive 2025/2) | transposition deadline | EU |
| 2027-01-30 | Solvency II Review (Directive 2025/2) | applies from | EU |
| 2027-07-10 | Bank Account Registries + BARIS (AMLD6 2024/1640 art. 16) | applies from | EU |
| 2027-07-10 | EU AML Package (AMLR 2024/1624 + AMLA 2024/1620) | applies from | EU |
What shifted this week
Demand by type of work, against its own 12-week average
Percentage difference from the same vertical’s recent baseline.
Whose technology is being named
VMware is the opening: it appears in 8 notices, 17% above its 12-week average of 6.8. The more consequential movement is downward. Microsoft has 4 notices and is down 23% against its 12-week average of 5.2; Dell has 3 and is down 53% against 6.3; Oracle has 1 and is down 54% against 2.2. Those falls are displacement signals for challengers, particularly where a buyer is moving from platform renewal into implementation or cloud service procurement.
Lenovo has 4 notices, IBM Cloud 3, Apple 2, and Red Hat, SAP and Starlink 1 each; no delta is reported for those vendors. CND's €2,000,000,000 French framework for servers, storage, backup and related services is the named tender to account-map against the VMware, Dell and Lenovo movements, although the data does not identify a vendor at individual-tender level. Repeat demand also deserves account planning: Rectorado de la Universidad de Sevilla has 6 tenders, Česká pošta has 3, Державне підприємство "Українські спеціальні системи" has 3, and the German federal procurement body acting for the Interior Ministry has 3.
Vendors named in this window’s tenders
Notices naming each vendor, with movement against the same vertical’s 12-week average.
Who is buying repeatedly
| Tenders | Buyer | Country | Example |
|---|---|---|---|
| 6 | Rectorado de la Universidad de Sevilla | ES | Spain – Computer equipment and supplies – Acuerdo Marco para el suministro, instalación y servicios asociados |
| 3 | Česká pošta, s.p. | CZ | Czechia – Servers – Dodávka APOST serverů |
| 3 | Державне підприємство "Українські спеціальні системи" | UA | Програмна продукція керування віртуальною інфраструктурою (код за ДК 021:2015 48210000-3 Пакети мережевого про |
| 3 | Bundesrepublik Deutschland, vertreten durch das Bundesministerium des Innern, vertreten durch das Beschaffungs | DE | Germany – IT services: consulting, software development, Internet and support – Rahmenvereinbarung über Techno |
| 2 | IWB Industrielle Werke Basel | CH | Switzerland – Information systems and servers – IWB, Server und Virtualisierungs-Infrastruktur |
| 2 | Miasto Stołeczne Warszawa | PL | Poland – Information systems and servers – Zakup serwerów, podzespołów oraz licencji oprogramowania |
| 2 | Fraunhofer-Gesellschaft - Einkauf B12 | DE | Germany – Data-processing services – Rahmenvereinbarung Quantencomputing Rechenzeit - PR1097780-3860-R |
| 2 | ДЕРЖАВНЕ ПІДПРИЄМСТВО "ІНФОТЕХ" | UA | Програмно-апаратний комплекс для модернізації, адміністрування, технічної підтримки центральної підсистеми ЄІС |
An organisation running several tenders in one window is usually working through a programme rather than buying once.
The biggest tenders
Published values total €2,890,699,521.88, but that covers only the 78 notices that published a value in EUR and is not the size of the market. The largest named opportunities are CND's €2,000,000,000 French framework for standardised and specialist servers, storage, backup and related services; RESAH's €500,000,000 acquisition of infrastructure solutions and associated services; Hansel Oy's €340,000,000 Pilvipalvelut 2026 cloud-services procurement; EuroHPC's €11,615,385 industrial-grade supercomputer acquisition; and Železnice Slovenskej republiky's €7,814,220.27 data-centre disk-array and SAN renewal. EuroHPC is the buyer with the clearest strategic build behind the tender: its mandate covers pooled procurement of high-performance and quantum computing infrastructure.
Values as published by the buyer, for the 78 of 208 tenders in this window that stated one in EUR.
Deadlines worth watching
Who won
Suppliers with the most awards this window
Awards published in the window, by named winner.
Sources consulted
Pages the writer read for context while drafting this column. The figures above come from the notices, not from these.
The next cloud bid plan should pair an AMLD6 register-and-interoperability offer with early qualification for CND's framework, while testing whether Spain's thin competition reflects a delivery-capacity gap that a specialist can genuinely fill.
Method
Built from 208 public procurement notices published between 2026-09-06 and 2026-09-20, classified into the Cloud & Infrastructure vertical. Every figure on this page is computed from those notices; the commentary is written around them. Sources: bzp, doe, ted, prozorro, worldbank. Tenders featured in earlier editions of this column are excluded from the named lists above.
Frequently Asked Questions
What is the current Cloud & Infrastructure procurement share?
The current share is 3.25%, a rise of 1.12 percentage points.
Where is competition most and least crowded?
Germany averages 3.6 bids, Poland 2.3 and Spain 1.7.
Which is the largest published-value tender?
CND's French framework for servers, storage, backup and related services has a published value of €2,000,000,000.