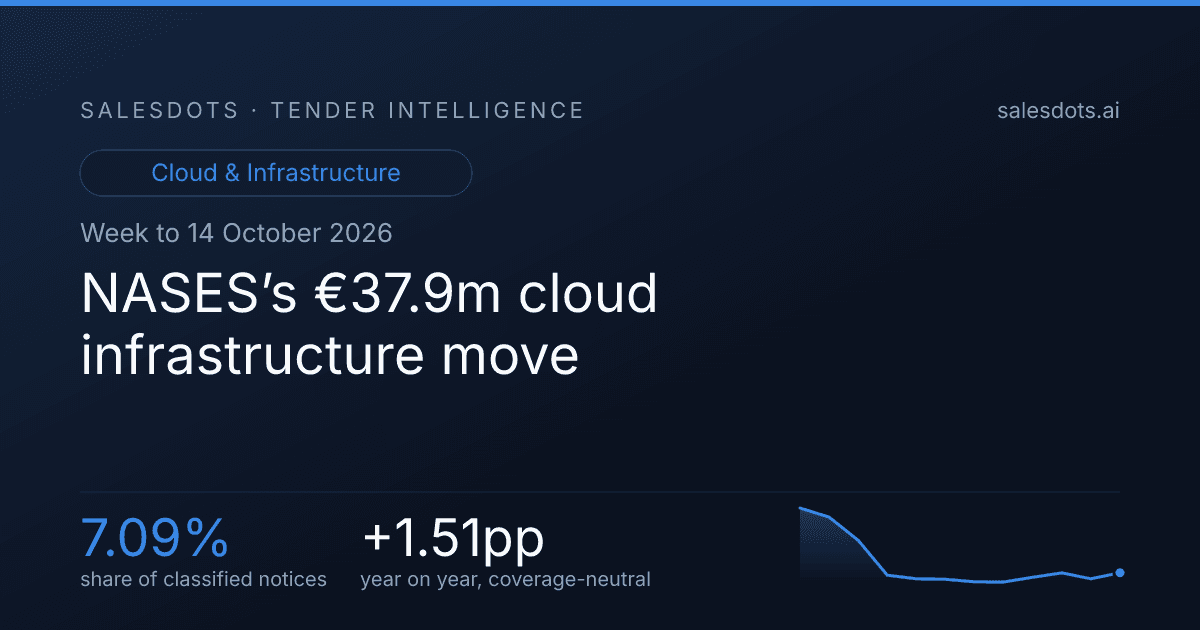
NASES’s €37.9m cloud infrastructure move
A Slovak government-cloud buyer leads disclosed values as cloud’s share jumps. Bid depth now determines whether to sell technical differentiation or delivery certainty.
Národná agentúra pre sieťové a elektronické služby has put €37.9m behind network and ICT components, the largest disclosed-value tender in this window. NASES is an operator of Slovak community-cloud services and has a role in the government-cloud strategy, making this a buyer worth treating as a state-cloud infrastructure account rather than a routine hardware refresh.
The immediate demand mix is broader than that headline deal. Hardware supply appears in 115 notices, but managed services appears in 54, licences and SaaS in 49, system implementation in 40 and support maintenance in 37. That gives account teams several routes into the same infrastructure cycle, particularly where an installed estate is moving from equipment purchase into operational support and subscription renewal.
Where this market is going
Cloud and Infrastructure now accounts for 7.09% of the classified corpus, a coverage-neutral rise of 1.51 percentage points. The monthly shape is lumpy rather than steady: share moved from 5.99% in October 2025 to 5.56% in November, 4.46% in December and 2.81% in January; it then sat at 2.64% in February, 2.62% in March, 2.5% in April and 2.49% in May. It recovered to 2.71% in June and 2.92% in July, slipped to 2.64% in August, then reached 2.93% in September before the current 7.09% reading.
The latest window is heavily above its 12-week norms in service-led buying. Support maintenance has 37 notices and a 563% delta, managed services has 54 and a 427% delta, while licences and SaaS has 49 and a 425% delta. Hardware supply has 115 notices and a 140% delta; system implementation has 40 and a 99% delta; custom development has 12 and a 58% delta. The sales implication is to lead with migration, operations and renewal narratives alongside infrastructure supply, not with hardware specifications alone.
Cloud & Infrastructure: share of all classified public IT tenders
Share, not volume. Monthly, last 12 complete months.
Where the tenders were published
Notices by buyer country, 7 days to 2026-10-14.
How hard the competition is
Czechia is the crowded market in this sample, at 5.8 bids per measured competition. There, technical differentiation, credible implementation method and quality evidence should carry the bid, particularly when competitors can all meet a basic infrastructure requirement. Poland sits at 3.1 bids, while Germany has 2.3 and Spain 2.2. France, at 1.5 bids, is the thin end of the market: qualification, local delivery capacity and a compliant route to contract are more likely to be the constraint than price alone.
The country contrast matters more than the blended 2.8-bid figure. The competition measure covers 77 procedures, with SMEs accounting for 72% of bids and single-bid outcomes at 49%. That is an SME-heavy field, but nearly half of the observed outcomes are not contested by multiple bidders. Price is recorded among 120 notices and quality among 38, yet a bidder entering France, Germany or Spain should first test eligibility, references and operational capacity; in Czechia, it should assume that those are merely the admission ticket.
How these contracts are awarded
Stated award criterion, for the tenders that declared one.
What is driving it
Poland’s uKSC is the immediate regulatory signal. It is cited in 5 tenders in this window, while its 30-day citation count is 253 compared with 247 in the preceding 30 days. The amended act requires entities classed as key or important to register, operate an information-security management system and report incidents. This is both compliance work and product procurement: advisory, governance and incident processes sit alongside secure hosting, infrastructure operations and security tooling.
The next financial-services pipeline is more compliance-led but creates platform work. The Solvency II Review has a transposition deadline of 29 January 2027 and applies from 30 January 2027, requiring insurers and supervisors to adapt reporting and risk frameworks. Bank Account Registries and BARIS apply from 10 July 2027, extending registry scope and requiring interconnection through BARIS by 10 July 2029: that is compliance work with a clear registry, data-integration and hosting component. NIS2 citations rose to 5 from 2, while DPM 2.0 remained at 1, CBAM fell to 0 from 1 and DORA fell to 0 from 1. Treat the latter signals as targeted account triggers, not broad infrastructure demand.
Regulations named in live tenders
Tenders citing each framework, last 30 days.
The calendar ahead
| Date | Framework | Milestone | Where |
|---|---|---|---|
| 2027-01-29 | Solvency II Review (Directive 2025/2) | transposition deadline | EU |
| 2027-01-30 | Solvency II Review (Directive 2025/2) | applies from | EU |
| 2027-07-10 | Bank Account Registries + BARIS (AMLD6 2024/1640 art. 16) | applies from | EU |
| 2027-07-10 | EU AML Package (AMLR 2024/1624 + AMLA 2024/1620) | applies from | EU |
What shifted this week
Demand by type of work, against its own 12-week average
Percentage difference from the same vertical’s recent baseline.
Whose technology is being named
Microsoft is the clearest named-vendor opening, appearing in 28 notices across 13 countries, with a 278% delta against its 12-week average. VMware appears in 20 notices across 11 countries and has a 229% delta; Dell has 8 notices and a 231% delta; HPE has 4 notices and an 85% delta. SAP has 8 notices, Red Hat 5, Oracle 4, IBM Cloud 4, HP Inc 3 and Fujitsu 3, but no delta is reported for those vendors. No named vendor has a negative delta in the supplied data, so there is no evidenced displacement story to call this week.
VMware is not an abstract signal: Komenda Główna Policji is a repeat buyer, with a named tender for VMware subscription licences among its 2 tenders. Other repeat demand includes Dirección General de Racionalización y Centralización de la Contratación-Junta de Contratación Centralizada, with 4 tenders including Ministry data-centre storage and backup expansion, and Fraunhofer-Gesellschaft - Einkauf B12, with 3 tenders including GPU systems for AI research. The payload does not map any named vendor to the largest disclosed-value tenders, so bidders should not attach Microsoft, VMware or Dell to the NASES, SANDETEL, HSE, ENEA or Wageningen opportunities without account-level evidence.
Vendors named in this window’s tenders
Notices naming each vendor, with movement against the same vertical’s 12-week average.
Who is buying repeatedly
| Tenders | Buyer | Country | Example |
|---|---|---|---|
| 4 | Dirección General de Racionalización y Centralización de la Contratación-Junta de Contratación Centralizada | ES | Spain – Computer equipment and supplies – Ampliación De La Infraestructura De Almacenamiento Y De Backup Del C |
| 3 | Fraunhofer-Gesellschaft - Einkauf B12 | DE | Germany – Information systems and servers – GPU-Rechner für KI-Anwendungen im Forschungsbereich Digital Busine |
| 2 | Státní pokladna Centrum sdílených služeb, s. p. | CZ | Czechia – Computer support and consultancy services – Provozní a odborná podpora infrastruktury datových cente |
| 2 | KOMENDA GŁÓWNA POLICJI | PL | Poland – Software package and information systems – Zakup subskrypcji licencji VMware |
| 2 | Polskie Sieci Elektroenergetyczne Spółka Akcyjna | PL | Poland – Compliance software package – Odnowienie subskrypcji IBM (dawniej Hashicorp) dla Platformy Konteneryz |
| 2 | ДЕРЖАВНЕ ПІДПРИЄМСТВО "ІНФОТЕХ" | UA | Програмне забезпечення віртуалізації для модернізації, адміністрування, технічної підтримки Єдиного державного |
| 2 | Entidad Pública Aragonesa de Servicios Telemáticos | ES | Spain – IT services: consulting, software development, Internet and support – Servicios de nube híbrida, gesti |
| 2 | AGENTIA DE PLATI SI INTERVENTIE PENTRU AGRICULTURA | RO | Romania – Computer-related professional services – ”Servicii de dezvoltare extindere si mentenanta a sistemulu |
An organisation running several tenders in one window is usually working through a programme rather than buying once.
The biggest tenders
The disclosed values cover only the 86 notices that published a value in euros, with a reported total of €165,090,534.78, and are not the size of the market. Beyond NASES’s €37.9m network and ICT-components purchase, SANDETEL has a €17.6m technical-infrastructure support tender while its wider Junta de Andalucía work includes a new data centre and consolidation across active-active data centres. HSE has a €17m Track and Trace support, maintenance and development requirement. ENEA has a €16.8m high-performance computing infrastructure tender for research centres, relevant to its Datacleen cloud and HPC ambitions within IPCEI-CIS. Wageningen University & Research has a €12.5m framework for server and storage systems.
Values as published by the buyer, for the 86 of 250 tenders in this window that stated one in EUR.
Deadlines worth watching
Who won
Suppliers with the most awards this window
Awards published in the window, by named winner.
Sources consulted
Pages the writer read for context while drafting this column. The figures above come from the notices, not from these.
Watch whether the service and subscription spike turns into named renewals at repeat buyers. The strongest next bids will connect compliance deadlines and sovereign operating requirements to a credible plan for running the infrastructure after it is installed.
Method
Built from 250 public procurement notices published between 2026-10-07 and 2026-10-14, classified into the Cloud & Infrastructure vertical. Every figure on this page is computed from those notices; the commentary is written around them. Sources: bzp, doe, ted, eop_bg, iub_lv, cvpis_lt, prozorro, sicap_ro. Tenders featured in earlier editions of this column are excluded from the named lists above.
Frequently Asked Questions
What is Cloud and Infrastructure’s current procurement share?
Cloud and Infrastructure accounts for 7.09% of the classified corpus, up 1.51 percentage points.
Where is cloud infrastructure competition most intense?
Czechia averages 5.8 bids, Poland 3.1, Germany 2.3, Spain 2.2 and France 1.5.
What is the largest disclosed-value tender?
Národná agentúra pre sieťové a elektronické služby has a €37,927,502.6 tender for network and ICT components.