EuroHPC’s €387.8m LUMI-AI tender resets cloud buying
A €387.8m supercomputer tender changes the near-term cloud pursuit list. Country bid gaps show where quality wins and where delivery capacity is the real constraint.
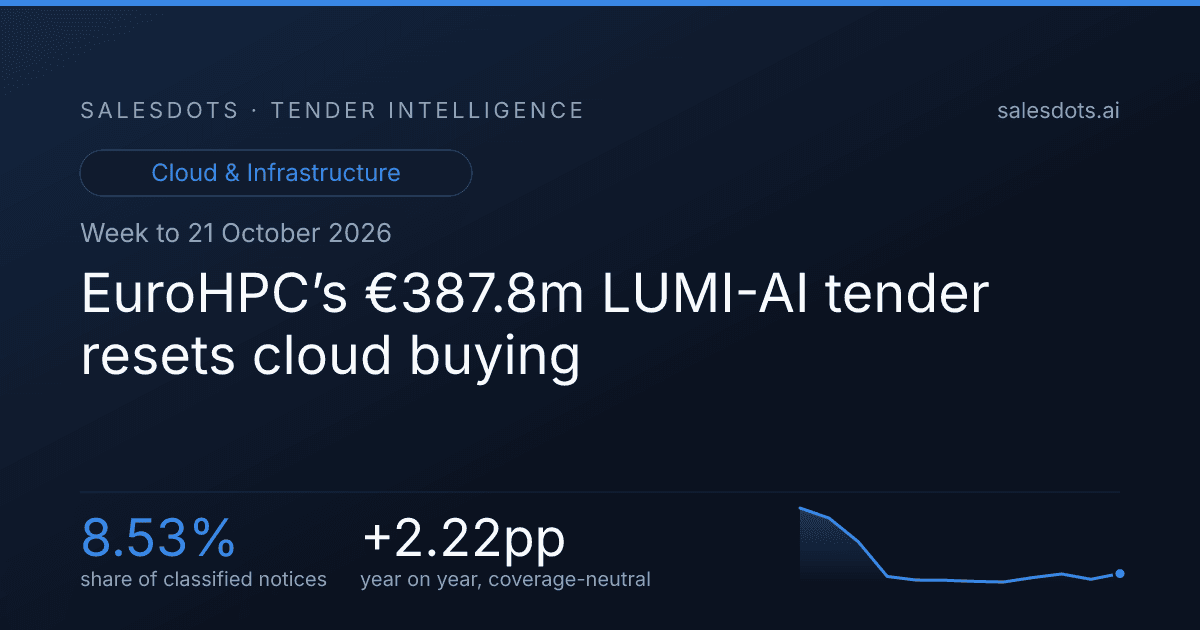
The European High Performance Computing Joint Undertaking has put a €387.8m LUMI-AI supercomputer acquisition into the market in Luxembourg. It is the largest tender among notices that published a euro value, and it makes the week’s cloud signal unusually concrete: acquisition, delivery, installation, and hardware and software maintenance are being bought together rather than separated into smaller pursuits.
That tender arrives in a 7-day window containing 318 notices from 287 buyers across 29 countries, with 186 deadlines still open. Hardware supply is the immediate pressure point, appearing in 177 notices against a 12-week weekly average of 56.7. Sellers with a credible route into large compute, storage and associated support should treat the EuroHPC notice as a pursuit signal, not merely an outlier in the data.
Where this market is going
Cloud and Infrastructure now accounts for 8.53% of the classified notice corpus, a coverage-neutral rise of 2.22 percentage points. The monthly path does not describe a steady expansion. Share fell from 6.07% in October 2025 to 5.59% in November, 4.47% in December and 2.82% in January 2026. It then levelled at 2.65% in February, 2.64% in March, 2.59% in April and 2.56% in May.
The recovery was equally uneven: 2.77% in June, 2.94% in July, back to 2.69% in August and 2.96% in September. This week’s 8.53% share is therefore a sharp current-window signal after a low, flat monthly run, not evidence of a smooth trend. Bid teams should qualify whether the current concentration is hardware-led before reallocating pursuit capacity away from application work.
Cloud & Infrastructure: share of all classified public IT tenders
Share, not volume. Monthly, last 12 complete months.
Where the tenders were published
Notices by buyer country, 7 days to 2026-10-21.
How hard the competition is
The country contrast should change how suppliers qualify. Romania averages 4 bids and Germany 3.8, compared with Poland at 2.4, Spain at 2.5 and the Czech Republic at 1.9. In Germany and Romania, assume a contested technical evaluation: differentiation, integration credibility and delivery evidence need to decide the bid. In the Czech Republic and Poland, a low bid count points instead to qualification, local delivery capacity and the ability to carry implementation risk. Price alone is unlikely to explain either market.
The blended average is 2.7 bids across the 105 notices where competition was measured, but it conceals a market where 42% are single-bid procedures. SMEs account for 63% of bids. The practical implication is that a supplier can still win by being eligible and ready when thinner contests emerge, while larger incumbents cannot assume that brand recognition will carry them through the German and Romanian fields.
How these contracts are awarded
Stated award criterion, for the tenders that declared one.
What is driving it
Poland’s uKSC is cited in 8 tenders in the current window. Its 30-day citation count is 222, compared with 278 in the preceding 30-day period. The act implements NIS2 obligations for key and important entities, so the buying implication is both compliance work and product procurement: security controls, resilient infrastructure and the services needed to operate them. NIS2 itself is flat at 3 citations in each 30-day period; DPM 2.0 is also flat at 1 in each; CBAM and DORA each stand at 0 after 1 in the prior period.
The next financial-services deadlines are more clearly implementation-led. The Solvency II Review requires transposition by 29 January 2027 and applies from 30 January 2027, driving reporting and risk-framework compliance work that can become platform and data-integration procurement. Bank-account registries extend scope from 10 July 2027 and must interconnect through BARIS by 10 July 2029. That is both compliance and product work: registry data models, searchable services, secure interfaces and the infrastructure to run them.
Regulations named in live tenders
Tenders citing each framework, last 30 days.
The calendar ahead
| Date | Framework | Milestone | Where |
|---|---|---|---|
| 2027-01-29 | Solvency II Review (Directive 2025/2) | transposition deadline | EU |
| 2027-01-30 | Solvency II Review (Directive 2025/2) | applies from | EU |
| 2027-07-10 | Bank Account Registries + BARIS (AMLD6 2024/1640 art. 16) | applies from | EU |
| 2027-07-10 | EU AML Package (AMLR 2024/1624 + AMLA 2024/1620) | applies from | EU |
What shifted this week
Demand by type of work, against its own 12-week average
Percentage difference from the same vertical’s recent baseline.
Whose technology is being named
Microsoft is named in 29 notices, 190% above its 12-week average; VMware appears in 20, up 164%; HPE in 9, up 272%; and Dell in 6, up 100%. These are openings rather than proof of awards, but the HPE surge is worth pursuing against EuroHPC’s €387.8m LUMI-AI supercomputer tender, where hardware supply, installation and maintenance are combined in one named requirement.
Red Hat is named in 5 notices, with no calculated delta reported; HP Inc is in 5, also with no reported delta; Oracle is in 5, with no reported delta; IBM Cloud is in 3, with no reported delta; SAP is in 3, with no reported delta; and Broadcom is in 3, with no reported delta. No negative vendor delta is reported in this extract, so there is no named-supplier displacement to call yet. The actual reversal sits in the offer mix: custom development is down 14% against its 12-week average, a reason to lead infrastructure pursuits with operating, support and migration capacity rather than standalone build teams.
Vendors named in this window’s tenders
Notices naming each vendor, with movement against the same vertical’s 12-week average.
Who is buying repeatedly
| Tenders | Buyer | Country | Example |
|---|---|---|---|
| 4 | Dirección General de Racionalización y Centralización de la Contratación-Junta de Contratación Centralizada | ES | Spain – Computer equipment and supplies – Adquisición De Varios Servidores Para Las Diferentes Redes Clasifica |
| 3 | Centrum e-Zdrowia | PL | Poland – Network equipment – Zakup urządzeń do awaryjnego przywracania usług w podmiotach dotkniętych incydent |
| 2 | The Office of Government Procurement | IE | Ireland – Computer equipment and supplies – DPS for the Provision of Compute and Storage Infrastructure and As |
| 2 | Hamburger Hochbahn AG | DE | Germany – Information systems and servers – Beschaffung von Serverhardware zur schrittweisen Modernisierung de |
| 2 | Wojewódzki Szpital Specjalistyczny im. Św. Jadwigi w Opolu | PL | Poland – Software package and information systems – Zakup, dostawa i wdrożenie w zakresie digitalizacji i cyfr |
| 2 | ENEA Operator sp. z o.o. | PL | Poland – Servers – Zakup serwerów dla potrzeb Projektu SCADA w Enea Operator sp. z o.o. |
| 2 | POLITECHNIKA RZESZOWSKA | PL | Poland – Servers – Dostawa serwerów do klastra wirtualizacyjnego |
| 2 | Urząd Regulacji Energetyki | PL | Poland – Operating systems – Dostawa licencjami oprogramowania serwerowego dla Urzędu Regulacji Energetyki. |
An organisation running several tenders in one window is usually working through a programme rather than buying once.
The biggest tenders
The largest published euro values cover only the 97 notices that disclosed a value in EUR, not the size of the market. After EuroHPC’s €387.8m LUMI-AI procurement, the Länder development consortium has an €86.5m GeFa testing and acceptance framework; Land Hessen’s central IT provider has a €45.8m framework for .NET, Java and related application development as Hesse pursues a multi-cloud model; Madrid’s municipal IT body has a €26.7m contract for its public-services platform while modernising the infrastructure beneath its private cloud; and the European Commission’s DG DIGIT has a €25.7m datacentre-infrastructure framework. Repeat demand reinforces the operational pipeline: Spain’s central procurement body appears in 4 tenders, Centrum e-Zdrowia in 3, and Ireland’s Office of Government Procurement in 2, with a largest published value of €500,000.
Values as published by the buyer, for the 97 of 318 tenders in this window that stated one in EUR.
Deadlines worth watching
Who won
Suppliers with the most awards this window
Awards published in the window, by named winner.
Sources consulted
Pages the writer read for context while drafting this column. The figures above come from the notices, not from these.
Watch whether the EuroHPC hardware signal produces follow-on installation and managed-service notices, and whether Poland’s lower-bid environment converts uKSC obligations into repeatable infrastructure lots before the regulatory calendar reaches its next deadlines.
Method
Built from 318 public procurement notices published between 2026-10-14 and 2026-10-21, classified into the Cloud & Infrastructure vertical. Every figure on this page is computed from those notices; the commentary is written around them. Sources: bzp, doe, ted, iub_lv, cvpis_lt, prozorro, sicap_ro. Tenders featured in earlier editions of this column are excluded from the named lists above.
Frequently Asked Questions
What is the current Cloud and Infrastructure share of notices?
8.53%, with a coverage-neutral rise of 2.22 percentage points.
Where is competition thinnest among the leading countries?
The Czech Republic averages 1.9 bids, compared with Poland at 2.4, Spain at 2.5, Germany at 3.8 and Romania at 4.
What is the largest tender with a published euro value?
The European High Performance Computing Joint Undertaking’s LUMI-AI supercomputer tender is valued at €387.8m.