SAP slips as Madrid tenders €67m NEXUS work
Madrid’s NEXUS contract is the week’s largest visible ERP deal, while SAP notice volume falls and country-level bid pressure splits sharply.
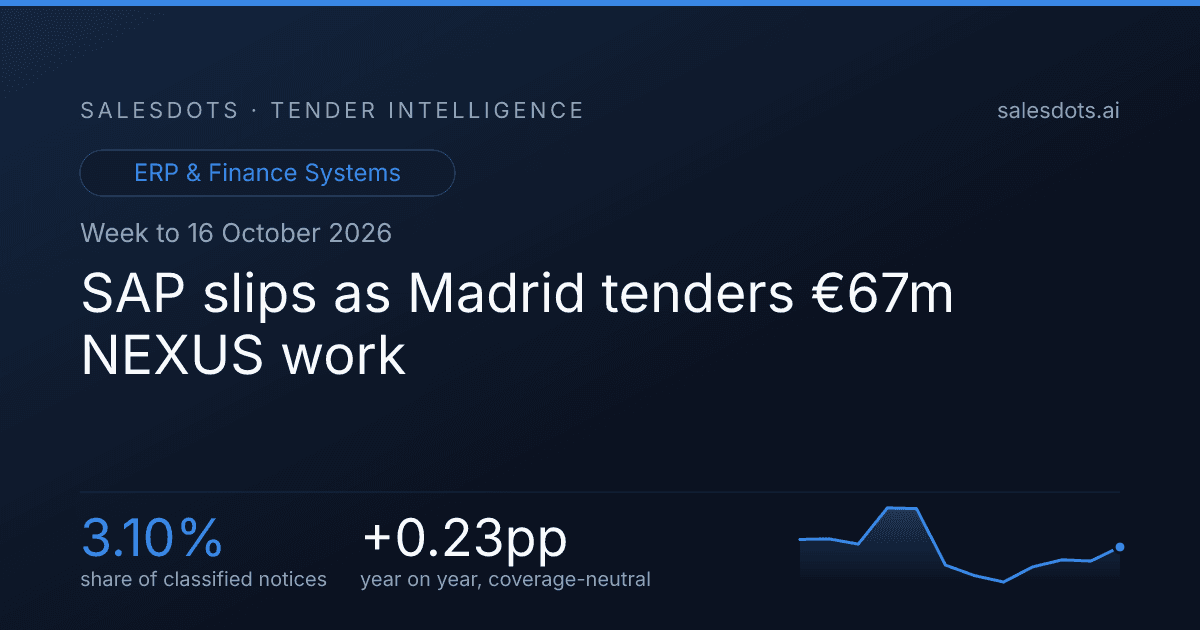
Agencia para la Administración Digital de la CM has put €66.7m behind maintenance and evolution of NEXUS ECCL, Madrid’s economic, budgetary and financial information system. It is the largest tender in this set and matters because the buyer is extending a platform that has already moved its financial and logistics estate forward, rather than launching a generic finance-system replacement. Suppliers should position around continuity, platform knowledge and controlled evolution, not a blank-sheet ERP proposition.
That tender sits in a 110-notice week spanning 106 buyers and 22 countries, with 66 notices still open to deadline. The immediate demand signal is implementation: 60 system-implementation notices are 298% above their twelve-week average. The counter-signal is custom development, with 11 notices, down 56%, suggesting buyers are currently more willing to buy transition and delivery capability than standalone bespoke build.
Where this market is going
ERP and finance systems account for 3.1% of the classified corpus, a coverage-neutral rise of 0.23 points. Do not mistake the 110 notices against 99 in the previous year for market growth: the usable measure is the share movement, not the raw count. The current share is above the previous-year share of 2.87%.
The monthly shape is lumpy rather than steady. Share moved from 2.43% in 2025-10 to 2.44% in 2025-11 and 2.35% in 2025-12, then jumped to 2.97% in 2026-01 and 2.96% in 2026-02. It dropped to 1.99% in 2026-03, 1.81% in 2026-04 and 1.7% in 2026-05, before recovering through 1.96% in 2026-06, 2.08% in 2026-07, 2.06% in 2026-08 and 2.3% in 2026-09. The present 3.1% is therefore a sharp upswing after an uneven recovery, not a smooth expansion.
ERP & Finance Systems: share of all classified public IT tenders
Share, not volume. Monthly, last 12 complete months.
Where the tenders were published
Notices by buyer country, 7 days to 2026-10-16.
How hard the competition is
The blended average of 3.5 bids conceals the decision that matters in pursuit selection. France averages 21 bids and Poland 7, where technical differentiation, credible references and a quality case will decide more than a lower rate card. Germany averages 2 bids, Spain 2.3 and Sweden 1.5. In those thinner fields, qualification, delivery capacity and an ability to take operational risk are the constraint: price alone will not create a credible bid where the buyer has few capable alternatives.
The competitive field is SME-heavy, with SME bids at 80%, while 41% of cases are single-bid situations. That combination argues against treating every notice as a large-incumbent contest. Open procedures account for 59 notices and negotiated procedures with a call for competition for 24, so early qualification work is particularly valuable in the low-bid countries. Where the field is crowded, the 17 quality-led awards offer a better route to differentiation than the 43 price-led cases.
How these contracts are awarded
Stated award criterion, for the tenders that declared one.
What is driving it
No regulation is cited directly in this tender set. The linked regulation signal is subdued rather than absent: NIS2 has 3 tenders in the past 30 days, against 4 in the preceding 30-day period; DPM 2.0 has 1 in each period; DORA has 0 after 1; and CBAM has 0 after 1. That makes compliance-led ERP demand a pipeline-building exercise, not a reason to expect an immediate wave of explicitly labelled tenders.
The calendar is nonetheless concrete. The Solvency II Review requires Member States to adopt and publish implementing measures by 29 January 2027 and applies from 30 January 2027, forcing insurance supervisors and insurers to adapt reporting and risk frameworks. Bank Account Registries and BARIS apply from 10 July 2027, requiring centralised mechanisms to identify account holders and controllers, with interconnection through BARIS by 10 July 2029. The EU AML Package also applies from 10 July 2027. For finance-system suppliers, this is both compliance work and product procurement: data models, reporting, audit trails, integrations and managed operational change will all be purchasable components.
Regulations named in live tenders
Tenders citing each framework, last 30 days.
The calendar ahead
| Date | Framework | Milestone | Where |
|---|---|---|---|
| 2027-01-29 | Solvency II Review (Directive 2025/2) | transposition deadline | EU |
| 2027-01-30 | Solvency II Review (Directive 2025/2) | applies from | EU |
| 2027-07-10 | Bank Account Registries + BARIS (AMLD6 2024/1640 art. 16) | applies from | EU |
| 2027-07-10 | EU AML Package (AMLR 2024/1624 + AMLA 2024/1620) | applies from | EU |
What shifted this week
Demand by type of work, against its own 12-week average
Percentage difference from the same vertical’s recent baseline.
Whose technology is being named
SAP is the more consequential movement: it is named in 16 notices across 7 countries, 24% below its twelve-week average of 21.1. That is not disappearance, but it is a displacement signal worth pursuing around incumbent estates. SAP competition is visible in NS Groep N.V.’s €35m SAP Expertise framework and Gemeente Amsterdam’s €19m Implementatie & Beheer Partner SAP tender. NS has been consolidating finance and logistics administration into a single SAP environment while continuing work on procurement and contract management, making implementation and application-management credentials more relevant than a generic software pitch. Microsoft moves the other way, appearing in 5 notices across 5 countries, 40% above its twelve-week average of 3.6.
Simple ERP appears in 4 notices and Unit4 in 2, but neither has a reported delta, so neither supports a momentum claim. The offering mix does: managed services has 12 notices and is 162% above its twelve-week average, licences and SaaS has 23 and is 142% above, while body leasing has 1 and is 69% below its twelve-week average. Repeat buying also identifies where persistence can matter. Centrum Usług Informatycznych we Wrocławiu has 3 ERP tenders, while Monetra Pohjois-Savo Oy has 2, including its payroll-system procurement.
Vendors named in this window’s tenders
Notices naming each vendor, with movement against the same vertical’s 12-week average.
Who is buying repeatedly
| Tenders | Buyer | Country | Example |
|---|---|---|---|
| 3 | Centrum Usług Informatycznych we Wrocławiu | PL | Poland – Software package and information systems – System klasy ERP, obejmujący obsługę kadrową, płacową, fin |
| 2 | Monetra Pohjois-Savo Oy | FI | Finland – Software package and information systems – Monetra E29/2026 / Palkanlaskentajärjestelmän hankinta hy |
| 2 | AEROPORTS DE PARIS | FR | France – IT services: consulting, software development, Internet and support – Prestation de fourniture de log |
An organisation running several tenders in one window is usually working through a programme rather than buying once.
The biggest tenders
The values here cover only the 33 notices that published a value in EUR, with €214.2m recorded across that subset, not the size of the market. Madrid’s €66.7m NEXUS ECCL maintenance and evolution contract leads the list. NS Groep N.V.’s €35m SAP Expertise procurement is a framework. Monetra Pohjois-Savo Oy’s payroll-system tender for wellbeing-services-county customers appears twice in the largest-tender list, each at €27.6m, and speaks to payroll and employment-lifecycle administration rather than a conventional general-ledger replacement. Gemeente Amsterdam’s €19m SAP implementation and management partner tender completes the visible large-deal cluster.
Values as published by the buyer, for the 33 of 110 tenders in this window that stated one in EUR.
Deadlines worth watching
Who won
Suppliers with the most awards this window
Awards published in the window, by named winner.
Sources consulted
Pages the writer read for context while drafting this column. The figures above come from the notices, not from these.
Prioritise the thin-bid German, Spanish and Swedish opportunities for qualified delivery teams, while using the Madrid, NS and Monetra programmes to map incumbent dependencies. The next contest will be won by suppliers that can turn compliance deadlines and estate modernisation into an implementable transition plan before the 66 open-deadline notices close.
Method
Built from 110 public procurement notices published between 2026-10-09 and 2026-10-16, classified into the ERP & Finance Systems vertical. Every figure on this page is computed from those notices; the commentary is written around them. Sources: bzp, doe, ted, iub_lv, prozorro, sicap_ro. Tenders featured in earlier editions of this column are excluded from the named lists above.
Frequently Asked Questions
What is the current procurement share for ERP and finance systems?
ERP and finance systems represent 3.1% of the classified corpus, up 0.23 points.
Where is ERP competition most and least crowded?
France averages 21 bids, Poland 7, Germany 2, Spain 2.3 and Sweden 1.5.
What is the largest published-value tender?
Agencia para la Administración Digital de la CM’s NEXUS ECCL maintenance and evolution tender is valued at €66,660,898.5.