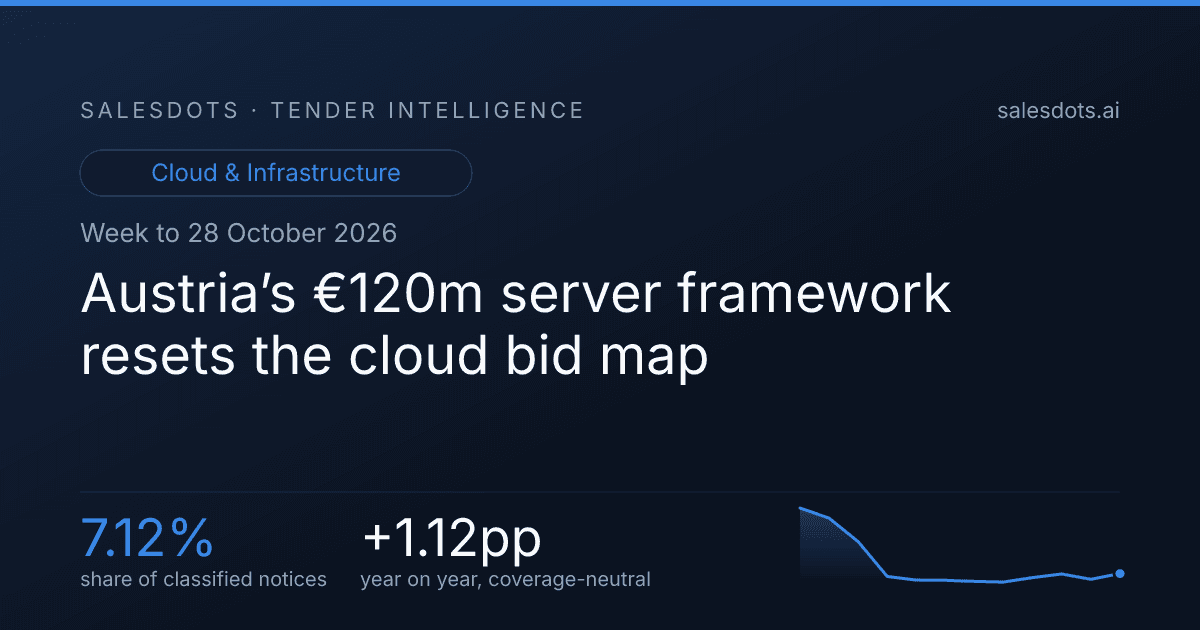
Austria’s €120m server framework resets the cloud bid map
Austria’s central buying model leads the week, while thin Spanish fields and a VMware surge change where suppliers should spend bid effort.
That buying move lands in a seven-day window of 278 notices from 253 buyers across 28 countries, with 171 still carrying an open deadline. The immediate sales question is not whether to chase volume indiscriminately, but whether a supplier can qualify for central routes such as Austria’s while retaining the delivery capacity to exploit the thinner national fields.
Where this market is going
The current mix is also pulling suppliers beyond equipment supply. Hardware supply appears in 136 notices, 100% above its twelve-week average, but managed services appears in 57 notices, up 205%, and licences and SaaS in 55, up 213%. Support and maintenance is in 36 notices, up 204%. A hardware-led account plan without renewal, subscription and operational-service coverage will miss much of the present demand.
Cloud & Infrastructure: share of all classified public IT tenders
Share, not volume. Monthly, last 12 complete months.
Where the tenders were published
Notices by buyer country, 7 days to 2026-10-28.
How hard the competition is
This is not a market in which every award becomes a multi-party price contest. The single-bid share is 41%, while the SME bid share is 77%, pointing to work that is often won by suppliers able to meet a defined local requirement rather than by the largest catalogue holder. In Spain, that favours early account coverage, references and operational readiness. In Romania and Czechia, use the same preparation time to sharpen architecture, migration and service-quality proof rather than merely cutting price.
How these contracts are awarded
Stated award criterion, for the tenders that declared one.
What is driving it
The nearer calendar creates both product procurement and compliance work. The Solvency II Review requires insurers and supervisors to adapt reporting and risk frameworks, with transposition due on 2027-01-29 and application from 2027-01-30. The European Health Data Space applies from 2027-03-26 and brings electronic health-data access and exchange, EHR-system requirements, self-certification and secondary-use arrangements. For cloud suppliers, these are not merely advisory engagements: they support demand for compliant data platforms, integration, hosting controls and the implementation work around them.
Regulations named in live tenders
Tenders citing each framework, last 30 days.
The calendar ahead
| Date | Framework | Milestone | Where |
|---|---|---|---|
| 2027-01-29 | Solvency II Review (Directive 2025/2) | transposition deadline | EU |
| 2027-01-30 | Solvency II Review (Directive 2025/2) | applies from | EU |
| 2027-03-26 | European Health Data Space (Regulation 2025/327) | applies from | EU |
| 2027-07-10 | Bank Account Registries + BARIS (AMLD6 2024/1640 art. 16) | applies from | EU |
| 2027-07-10 | Bank Account Registries + BARIS (AMLD6 2024/1640 art. 16) | transposition deadline | EU |
| 2027-07-10 | EU AML Package (AMLR 2024/1624 + AMLA 2024/1620) | applies from | EU |
What shifted this week
Demand by type of work, against its own 12-week average
Percentage difference from the same vertical’s recent baseline.
Whose technology is being named
There is no evidenced displacement story among the named vendors this week: none sits below its stated twelve-week average. Cisco has 6 notices with no delta reported; Broadcom, Veeam and Omnissa have 3 each with no delta reported; and Red Hat has 2 with no delta reported. VMware’s activity has a named repeat-buyer location at Centrum Informatyki Resortu Finansów, whose example tender is for VMware vSphere subscriptions. The largest-tender list itself does not attribute a vendor to any of its entries, so it would be unsafe to assign VMware, Dell or another supplier to Austria’s SSN 2026-3, PIAST or the Spanish contracts.
Vendors named in this window’s tenders
Notices naming each vendor, with movement against the same vertical’s 12-week average.
Who is buying repeatedly
| Tenders | Buyer | Country | Example |
|---|---|---|---|
| 6 | Universitätsklinikum Frankfurt | DE | Germany – Software package and information systems – Bereitstellung einer KI-Compute-, Entwick lungs- und Inte |
| 4 | Dirección General de Racionalización y Centralización de la Contratación-Junta de Contratación Centralizada | ES | Spain – Software package and information systems – Renovación De La Solución Software De Backup Y Almacenamien |
| 3 | Ministerstvo vnitra | CZ | Czechia – Servers – Modernizace datové infrastruktury NCTEKK pro boj s kyberkriminalitou |
| 3 | Junta de Gobierno del Ayuntamiento de Torrent | ES | Spain – World wide web (www) site operation host services – Servicio de computación en la nube para el Ayuntam |
| 3 | Województwo Mazowieckie | PL | Poland – IT services: consulting, software development, Internet and support – Zakup usługi eksperckiego wspar |
| 2 | Technische Hochschule Brandenburg | DE | KI-Labor: GPU-Tower |
| 2 | Conseil Départemental du Nord | FR | France – Hardware integration consultancy services – Accord-cadre à bons de commande et à marchés subséquents |
| 2 | Centrum Informatyki Resortu Finansów | PL | Poland – Software package and information systems – Dostawa oprogramowania Vmware vSphere w modelu subskrypcyj |
An organisation running several tenders in one window is usually working through a programme rather than buying once.
The biggest tenders
The listed values cover only the 99 notices that published a value in euros, not the size of the market; those notices total €322.3m. Austria’s Republic and BBG lead with the €120m SSN 2026-3 servers framework. The European High-Performance Computing Joint Undertaking follows with the €59.5m PIAST AI-Optimised Supercomputer, consistent with its role in shared European supercomputing infrastructure. Madrid’s Organismo Autónomo Informática has a €26.9m contract for maintenance, support and evolution of its urban public-services platform, while its wider modernisation work includes private-cloud data-centre renewal and preparation for public-cloud use. Sandetel has a €17.6m technical-infrastructure support requirement, and Galicia’s technology-modernisation agency has a €13.3m systems-administration service.
Values as published by the buyer, for the 99 of 278 tenders in this window that stated one in EUR.
Deadlines worth watching
Who won
Suppliers with the most awards this window
Awards published in the window, by named winner.
Sources consulted
Pages the writer read for context while drafting this column. The figures above come from the notices, not from these.
Watch whether Austria’s framework attracts suppliers able to turn central qualification into repeat call-off delivery, while Spain’s low-bid field rewards firms that arrive with named capacity rather than a late price response.
Method
Built from 278 public procurement notices published between 2026-10-21 and 2026-10-28, classified into the Cloud & Infrastructure vertical. Every figure on this page is computed from those notices; the commentary is written around them. Sources: bzp, doe, ted, eop_bg, cvpis_lt, prozorro, sicap_ro. Tenders featured in earlier editions of this column are excluded from the named lists above.
Frequently Asked Questions
Which country has the highest average bid count?
Romania averages 6 bids. Czechia averages 3.6, Poland 2.9, Germany 2.7 and Spain 1.6.
Which named vendor moved most sharply?
VMware appears in 29 notices and is up 225% against a twelve-week average of 8.9.
What is the largest named cloud and infrastructure tender?
SSN 2026-3 for Austria’s Republic and Bundesbeschaffung GmbH is valued at €120m and is a framework.