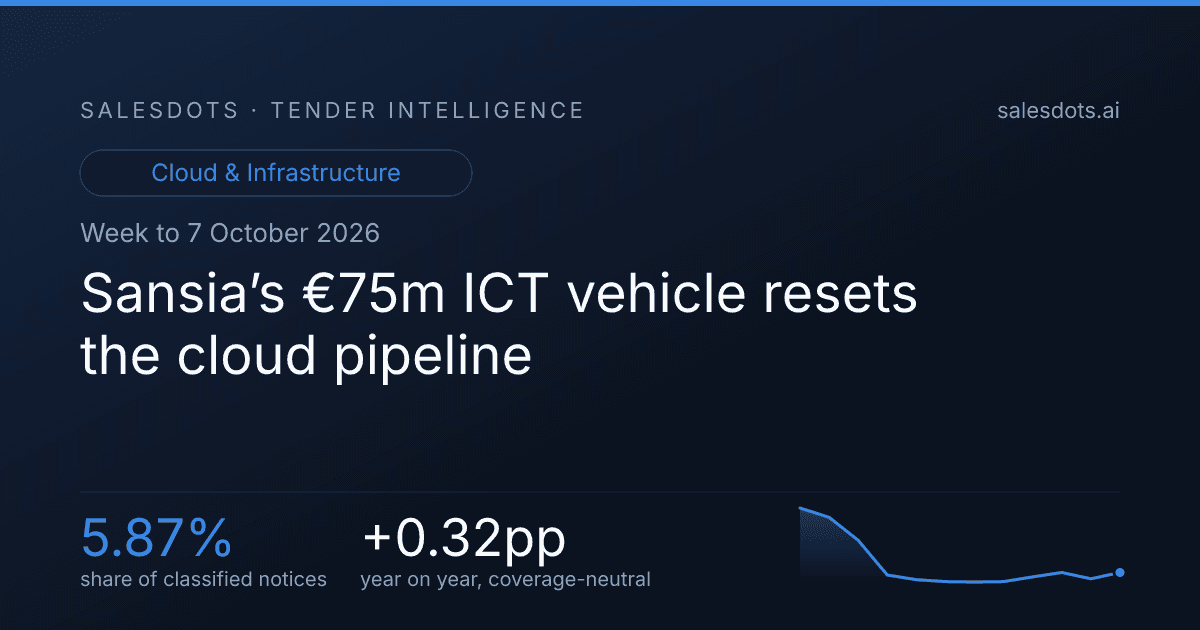
Sansia’s €75m ICT vehicle resets the cloud pipeline
A Finnish procurement vehicle dominates the largest notices while virtualisation, licences and maintenance surge. Bid strategy now depends on country-level competition.
Sansia Oy has placed the same €75m ICT equipment and supplies dynamic purchasing system into the biggest-tender list three times. That matters because Sansia is a procurement vehicle for public-sector owner-customers, not a buyer with a disclosed cloud build-out: suppliers should treat this as a route into a pooled pipeline, not as a single infrastructure deployment.
The immediate contest also includes ProVitako Marketing- und Dienstleistungsgesellschaft der Kommunalen IT-Dienstleister e.G.’s €30.9m Virtualisierungsalternativen framework in Germany. Across the seven-day window there are 201 notices from 181 buyers in 28 countries, with 115 deadlines still open. Sansia appears in three notices and ProVitako in two, making repeat procurement vehicles more important than a notice-by-notice pursuit plan.
Where this market is going
Cloud and infrastructure now accounts for 5.87% of classified notices, a rise of 0.32 percentage points on the comparable share. The current position is notably above the monthly pattern: share moved from 5.96% in October 2025 to 5.52% in November and 4.43% in December, then fell through 2.78% in January, 2.56% in February, 2.47% in March and 2.45% in April 2026. It recovered to 2.47% in May, 2.69% in June and 2.9% in July, slipped to 2.6% in August, then returned to 2.9% in September.
This is a lumpy recovery rather than a steady climb, with the latest seven-day share breaking well above the recent monthly range. The offer mix explains the abruptness: licences and SaaS has 47 notices and is 781% above its twelve-week average; support and maintenance has 23 notices and is 590% above; managed services has 33 and is 350% above. Hardware supply remains the volume engine at 94 notices, 122% above average, while custom development has five notices and is 34% below average. Lead with packaged platforms, migration support and ongoing operation, rather than assuming buyers are commissioning bespoke builds.
Cloud & Infrastructure: share of all classified public IT tenders
Share, not volume. Monthly, last 12 complete months.
Where the tenders were published
Notices by buyer country, 7 days to 2026-10-07.
How hard the competition is
The commercial terrain changes sharply by country. Bulgaria is the crowded end at 3.3 bids per tender, Germany records 2.5 and Spain 2.4, where differentiation, technical quality and a credible operating model should decide the pursuit. Poland averages 2.1 bids and Czechia 1.8. In those thinner contests, qualification, local delivery capacity and the ability to mobilise matter more than price alone: a technically acceptable bidder that cannot evidence capacity may simply leave the field open to an incumbent.
The 2.5-bid average is measured on 52 tenders, but the country contrast is the actionable signal. SMEs account for 60% of the measured bidding picture, while 38% of tenders draw a sole bid. That combination says this work is not reserved for the largest integrators, but it also warns against interpreting a low bid count as an easy price-led sale. Spain’s Dirección General de Racionalización y Centralización de la Contratación-Junta de Contratación Centralizada has four tenders in the window, while Czechia’s Ministerstvo vnitra has three, making both repeat-buyer accounts worth structured coverage.
How these contracts are awarded
Stated award criterion, for the tenders that declared one.
What is driving it
Poland’s Ustawa o krajowym systemie cyberbezpieczeństwa, or uKSC, is the immediate citation signal: 261 tenders cite it in the latest 30 days, against 239 in the preceding 30 days, and two tenders cite it in the current window. The amended regime requires covered entities to register and connect to the national cybersecurity system. That is both compliance work and product procurement, particularly where registration, security operations and infrastructure controls need to be made operational. NIS2 has four citations in the latest 30 days against three previously, while DPM 2.0 has two against none previously, pointing to a smaller but live reporting and supervisory-data opportunity.
The next public-financial-authority work is more visibly compliance-led, with infrastructure consequences. The Solvency II Review requires insurers and supervisors to adapt reporting and risk frameworks by 29 January 2027, with measures applying from 30 January 2027. Bank Account Registries and BARIS require centralised mechanisms for identifying account holders and controllers, with the expanded scope applying from 10 July 2027 and interconnection through BARIS by 10 July 2029. Sellers should position data platforms, identity controls, integration and hosting alongside regulatory implementation, not as standalone cloud propositions.
Regulations named in live tenders
Tenders citing each framework, last 30 days.
The calendar ahead
| Date | Framework | Milestone | Where |
|---|---|---|---|
| 2027-01-29 | Solvency II Review (Directive 2025/2) | transposition deadline | EU |
| 2027-01-30 | Solvency II Review (Directive 2025/2) | applies from | EU |
| 2027-07-10 | Bank Account Registries + BARIS (AMLD6 2024/1640 art. 16) | applies from | EU |
| 2027-07-10 | EU AML Package (AMLR 2024/1624 + AMLA 2024/1620) | applies from | EU |
What shifted this week
Demand by type of work, against its own 12-week average
Percentage difference from the same vertical’s recent baseline.
Whose technology is being named
VMware is the clearest movement signal, named in 17 notices across nine countries and 240% above its twelve-week average. Microsoft follows with 16 notices across 10 countries, 170% above average. HPE has five notices and is 131% above, while Dell has three and is 24% above. These are openings for rivals where licensing, support renewal and platform transition create reasons to challenge installed estates, rather than merely defend hardware positions.
There is no reported negative vendor delta in this window, so there is no named displacement signal to over-read. SAP has seven notices with no delta recorded; Cisco has six with no delta recorded; Oracle has four, Broadcom three, Nintex two and Nvidia two, all without a recorded delta. VMware’s surge is the backdrop to the market ProVitako has brought to tender through its Virtualisierungsalternativen framework: the fight is visibly moving into municipal IT procurement channels, not only into isolated central-government requirements.
Vendors named in this window’s tenders
Notices naming each vendor, with movement against the same vertical’s 12-week average.
Who is buying repeatedly
| Tenders | Buyer | Country | Example |
|---|---|---|---|
| 4 | Dirección General de Racionalización y Centralización de la Contratación-Junta de Contratación Centralizada | ES | Spain – Computer equipment and supplies – 2026/Sp02002001/00001520E - Sostenimiento De Equipos De Infraestruct |
| 3 | Sansia Oy | FI | Finland – Computer equipment and supplies – ICT laitteiden ja tarvikkeiden dynaaminen hankintajärjestelmä |
| 3 | Ministerstvo vnitra | CZ | Czechia – Network equipment – Obměna serverové VT |
| 2 | Samorządowy Zakład Opieki Zdrowotnej w Pińczowie | PL | „Wsparcie podstawowej opieki zdrowotnej (POZ)”, nr projektu FENX.06.01-IP.03-0001/23 – Dostawa serwerów do arc |
| 2 | IT-Services der Sozialversicherung GmbH | AT | Austria – Servers – Cisco |
| 2 | ProVitako Marketing- und Dienstleistungsgesellschaft der Kommunalen IT-Dienstleister e.G. | DE | Germany – Software package and information systems – Virtualisierungsalternativen |
| 2 | Netze Duisburg GmbH | DE | Germany – Software package and information systems – Workforcemanagementsystem - Netzbau (WFM BAU) |
| 2 | ИНФОРМАЦИОННО ОБСЛУЖВАНЕ АД | BG | Bulgaria – Communications system maintenance services – „Изграждане на комуникационна свързаност и поддръжка н |
An organisation running several tenders in one window is usually working through a programme rather than buying once.
The biggest tenders
The published-value subset covers 77 notices and totals €343.7m, not the size of the market. Sansia’s €75m dynamic purchasing system is the largest listed opportunity and appears three times. ProVitako’s €30.9m German virtualisation framework is the largest named municipal IT channel, while Centrum vedecko-technických informácií Slovenskej republiky has a €25.3m Slovak tender for digital transformation and modernisation of ICT infrastructure and IT systems. The Sansia route is a pooled procurement mechanism; ProVitako aggregates municipal IT requirements. Both therefore reward account plans that address the procurement vehicle and its downstream users.
Values as published by the buyer, for the 77 of 201 tenders in this window that stated one in EUR.
Deadlines worth watching
Who won
Suppliers with the most awards this window
Awards published in the window, by named winner.
Sources consulted
Pages the writer read for context while drafting this column. The figures above come from the notices, not from these.
Watch whether the current licence, maintenance and managed-service spike turns into awarded platform transitions before the open deadlines close. The strongest next bids will pair compliance delivery with an account-specific route through repeat buyers such as Sansia, ProVitako and central purchasing bodies.
Method
Built from 201 public procurement notices published between 2026-09-30 and 2026-10-07, classified into the Cloud & Infrastructure vertical. Every figure on this page is computed from those notices; the commentary is written around them. Sources: bzp, doe, ted, eop_bg, iub_lv, prozorro, sicap_ro, worldbank. Tenders featured in earlier editions of this column are excluded from the named lists above.
Frequently Asked Questions
How large is the current Cloud & Infrastructure notice flow?
The seven-day window contains 201 notices from 181 buyers across 28 countries, with 115 deadlines open.
Where is competition thinnest and deepest?
Czechia averages 1.8 bids, Poland 2.1, Spain 2.4, Germany 2.5 and Bulgaria 3.3.
What do the published tender values cover?
Published EUR values cover 77 notices, totalling €343,716,235.43, with a median of €1,179,750.